
Homeowners Insurance in Pembroke Pines, FL
Pembroke Pines homeowners can face varying home insurance premiums depending on their property and coverage needs. Understanding what drives those costs and how to manage them starts with knowing what makes this western Broward County suburb unique from an insurance perspective.
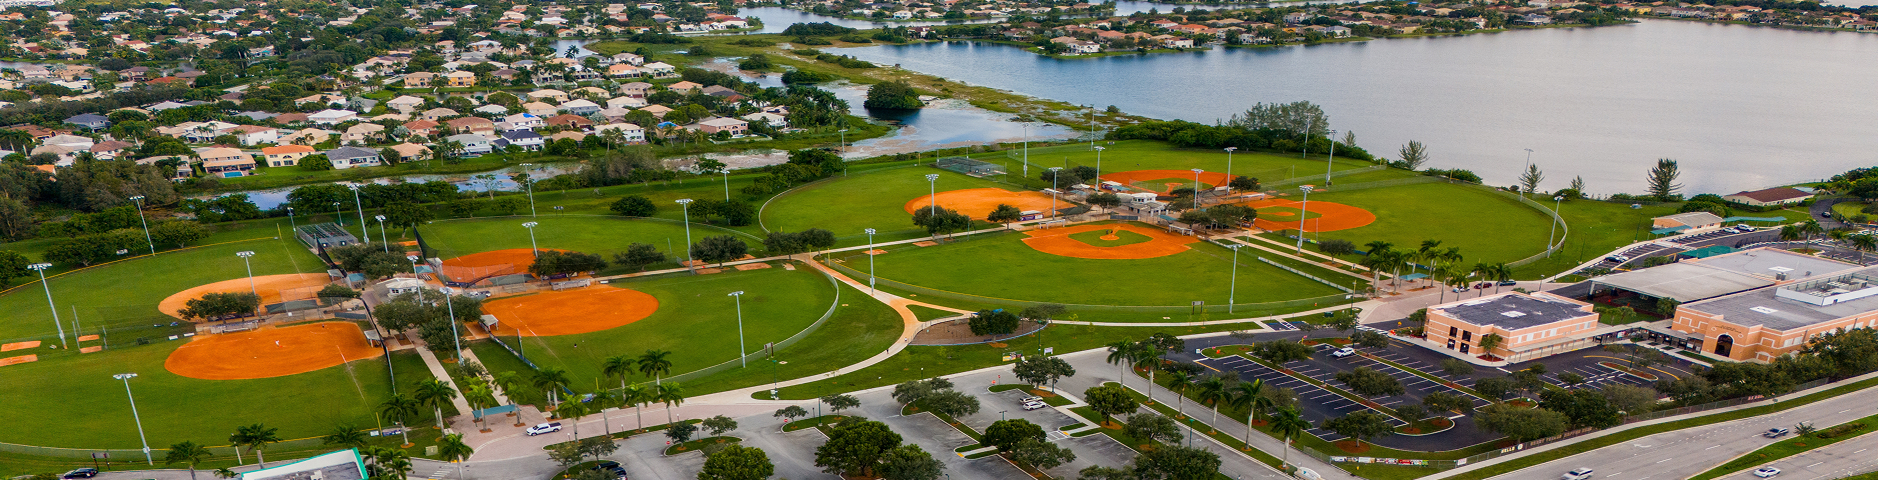
Pembroke Pines stretches across a patchwork of communities, from Chapel Trail to the condos near City Center and the established neighborhoods around Silver Lakes. Housing types include single-family detached homes, townhomes, gated communities like Pembroke Falls and Grand Palms, and 55+ villages such as Century Village. That diversity means Pembroke Pines residents may have different insurance needs.
Homeowners insurance is not legally required in Florida, but mortgage lenders generally require property coverage. Even if you own your home outright, coverage can help protect against risks South Florida homeowners face, including hurricane damage, theft, and fire. A standard home insurance policy typically covers dwelling, personal property, and liability, giving you a financial foundation when the unexpected strikes.
Homeowners insurance in Pembroke Pines can cover dwelling and personal property, but it’s important to understand what’s excluded. Flood damage, for example, generally requires a separate policy. InsureOne compares quotes from multiple carriers, helping Pembroke Pines residents explore homeowners insurance in Florida without calling every insurer individually.
How Much Does Homeowners Insurance Cost in Pembroke Pines, FL?
Home insurance rates in Pembroke Pines vary based on property characteristics, coverage needs, and insurer underwriting factors.
Rates depend on dwelling coverage amount, year built, construction type, roof age and condition, claims history, and the deductible you select. Homeowners insurance in Florida can vary based on the home’s characteristics and conditions, and newer homes built to modern Florida Building Code standards may qualify for better rates because of their construction features.

Local Risks That Affect Pembroke Pines Homeowners Insurance Rates
Insurers evaluate both property-specific details and potential risks when setting premiums. Here are factors that may affect your home insurance rates.
Hurricanes and Tropical Storms – Hurricane damage is a risk in Pembroke Pines. Atlantic hurricane season runs June through November, and windstorm and hurricane damage are common coverage considerations for Florida homeowners insurance. Even storms that don’t make direct landfall can deliver damaging winds, flying debris, and structural harm to roofs and exterior walls across South Florida.
Flooding and Flood Maps – Flood zone designations can affect insurance requirements and costs. Flood insurance may be required for certain homes in high-risk flood zones with federally backed mortgages. Flood damage is generally excluded from standard homeowners insurance policies, so a separate flood policy may be needed for additional protection.
Severe Thunderstorms – Pembroke Pines experiences summer storms that can bring lightning, hail, and sudden high winds. These events can cause property damage to roofs, fencing, pool enclosures, and landscaping.
Heat and Humidity – South Florida’s heat can strain heating, ventilation, and air conditioning (HVAC) systems and create conditions for mold and moisture damage in homes. Mold coverage varies by policy, making water damage prevention important.
Theft and Property Crime – Theft and vandalism are risks homeowners may want to consider when reviewing their coverage. Installing protective devices, including monitored alarms, deadbolts, and security cameras, may help reduce these risks.
Aging Infrastructure – Older homes may have electrical, plumbing, and roofing systems that increase risk. Homeowners insurance policies in Florida often evaluate the roof’s age and condition for coverage eligibility.
Mitigation steps that may help improve your risk profile include installing hurricane shutters or impact-resistant windows, upgrading roofing materials, modernizing wiring and plumbing, and maintaining tree clearances around the home.
Coverage Pembroke Pines, FL, Homeowners Often Consider
A standard home insurance policy typically covers dwelling, other structures, personal property, loss of use, liability, and medical payments, subject to policy terms and limits. Homeowners insurance may include loss of use coverage if the home is uninhabitable after a covered disaster. Beyond the basics, Pembroke Pines residents can consider these coverage options for extra protection:
- Extended Replacement Cost Coverage – Helps rebuild your home if covered construction costs exceed your dwelling coverage limit, subject to policy terms and limits.
- Hurricane Deductibles and Windstorm Coverage – Windstorm damage may have a separate deductible in Florida policies. Your hurricane deductible depends on your policy terms and coverage amount.
- Water Backup and Sump Pump Overflow – May cover certain damage from sewer backups and drainage system overflows. This endorsement is typically not included in standard policies.
- Flood Insurance – Since standard homeowners insurance in Florida generally excludes flood damage, Pembroke Pines residents may want to consider a separate flood insurance policy.
- Scheduled Personal Property – Additional personal property coverage may be available for jewelry, electronics, collectibles, or musical instruments that exceed standard policy limits on personal belongings. Homeowners with valuable jewelry can also explore jewelry insurance.
- Pool and Outdoor Structure Coverage – Pool enclosures, detached garages, fences, and pergolas may fall under other structures coverage, depending on the policy. Homeowners with these features should review their coverage limits.
- Equipment Breakdown Coverage – May cover certain HVAC failures, water heaters, and other mechanical breakdowns, depending on policy terms and exclusions.
- Umbrella Liability Coverage – For homeowners with pools, higher-value properties, or significant personal assets, umbrella liability insurance may provide additional liability coverage beyond standard policy limits.
InsureOne agents can help you explore coverage types based on your property, neighborhood, and budget.
How Home Insurance Costs Can Vary Across Pembroke Pines Neighborhoods
Home insurance rates can vary based on neighborhood and property risk profile. Two similar homes a few miles apart may carry different premiums due to construction age, elevation, flood zone designation, and local conditions.
- Chapel Trail (33029) – Homeowners should consider their property’s construction features, roof condition, and available wind mitigation measures when comparing insurance options.
- City Center – Condo and townhome owners should review their coverage needs, including any applicable association master policies.
- Grand Palms (33028) – Homeowners should review property-specific flood exposure, construction characteristics, and coverage limits when comparing insurance options.
- Silver Lakes (33023/33028) – Roof condition, mitigation features, claims history, and flood zone designation may affect insurance premiums and coverage needs.
- Pembroke Falls – Homeowners should consider their property’s replacement cost, dwelling coverage, and liability limits when selecting a policy.
- Areas Near I-75 and Florida’s Turnpike – Homeowners should review their property’s individual characteristics and coverage needs when comparing insurance options.
InsureOne can help customers across Pembroke Pines compare quotes based on their individual property details and coverage needs. Understanding which homes need more insurance can also help homeowners evaluate their coverage requirements.

Types of Home Insurance Policies Available to FL Residents
Pembroke Pines residents and property owners can choose from several types of home insurance policies depending on their living situation:
- Standard Homeowners (HO-3/HO-5) – For eligible owner-occupied houses and townhomes, covering the structure and personal belongings against covered perils. Homeowners insurance may cover dwelling, personal property, and liability under these policy forms.
- Condo Insurance (HO-6) – For Pembroke Pines condo owners needing interior coverage and liability, coordinated with their association’s master policy. Depending on the master policy, unit improvements, personal property coverage, and personal liability may require separate HO-6 coverage.
- Renters Insurance (HO-4) – For tenants in Pembroke Pines apartments, covering personal property and liability but not the building structure itself, subject to policy terms.
- Landlord/Dwelling Policies (DP-3) – For eligible property owners renting out homes or other properties, focusing on the structure and potentially providing lost rental income and landlord liability coverage.
- Mobile Home Insurance – For eligible manufactured housing, covering the structure and contents with policies tailored to mobile and manufactured homes.
InsureOne can help Pembroke Pines families and investors explore available policy types and potential insurance bundling opportunities.
Ways Pembroke Pines Homeowners Can Save on Insurance
Pembroke Pines homeowners may have several ways to save on homeowners insurance:
- Bundle Home and Auto Insurance – Bundling home and auto insurance may help lower premiums, depending on the insurer and available discounts.
- Install Hurricane Mitigation Features – Hurricane straps and secure roof-to-wall connections are wind mitigation features that may help lower premiums. Impact-resistant windows, storm shutters, and reinforced entry doors may also qualify for discounts, depending on the insurer.
- Complete a Wind Mitigation Inspection – A wind mitigation inspection can document qualifying features that may help homeowners obtain available insurance discounts.
- Add Monitored Security Systems – Installing protective devices like burglar alarms, smoke and carbon monoxide detectors, and water leak sensors may qualify for insurance discounts while helping reduce the risk of theft and water damage.
- Maintain a Claims-Free Record – A clean claims history may help homeowners qualify for discounts with certain insurers.
- Choose a Higher Deductible – Raising your deductible can help reduce your insurance premium, though you should balance potential savings against higher out-of-pocket costs.
- Update Older Home Systems – Replacing roofing, electrical, and plumbing systems in older homes may help improve safety and insurance eligibility. Roof age and material can be factors in Florida underwriting.
- Explore Carrier-Specific Credits – New home discounts, renovation credits, and paperless billing options may be available through participating insurance carriers.
Schedule a coverage review with an InsureOne agent to check for available discounts and adjust policy limits as home values change.

Get Homeowners Insurance in Pembroke Pines, FL With InsureOne
Choosing the right Pembroke Pines home insurance is important whether you live in a gated community in Pembroke Falls, a condo near City Center, or a single-family home in Chapel Trail. The right policy can help protect your property against covered losses from hurricanes, theft, liability, and other risks across South Florida. Flood damage generally requires separate coverage.
InsureOne serves as your insurance concierge for Florida, shopping multiple carriers, providing personalized guidance on coverage options and deductibles, and helping you explore home, auto, business insurance, and other policies. Our Florida insurance agents can help you review coverage options that fit your specific needs and budget.
- Get a free quote online
- Call us at 800-836-2240 to speak directly with an agent
- Visit a local Florida office for in-person service
With the right homeowners insurance in Pembroke Pines, you can have confidence that your home and personal assets have protection against covered risks, subject to policy terms, conditions, and exclusions.
Frequently Asked Questions About Home Insurance in Paterson, NJ
Is Homeowners Insurance Required in Paterson, NJ?
It is not legally required by the state of New Jersey, but virtually all mortgage lenders require it to protect their collateral. Even without a mortgage, insurance coverage is strongly recommended given Paterson’s weather risks, older housing stock, and liability exposure. A standard policy covers dwelling damage, personal property loss, liability, and loss of use, providing comprehensive protection for your residence.
Do Paterson Homeowners Near the Passaic River Need Flood Insurance?
Yes. Standard homeowners insurance policies do not cover flood damage, and properties in FEMA Special Flood Hazard Areas (Zones A, AE, and others) along the Passaic River are typically required to carry separate flood insurance when holding a federally backed mortgage. Flooding can also occur outside high-risk zones, so homeowners in lower-lying areas may want to consider flood insurance. InsureOne can help you check your property’s flood exposure and request a policy.
What Factors Most Affect Home Insurance Rates in Paterson Neighborhoods?
Location within the city, year built, roof condition, claims history, coverage limits, deductibles, and credit-based insurance score all play a role. Paterson-specific factors include flood zone designation, neighborhood crime rates, construction materials (especially in historic preservation districts), and the condition of major systems like electrical, plumbing, and HVAC. Home insurance premiums can vary between Paterson neighborhoods based on property characteristics and the factors each insurer considers.
How Do Paterson’s Older Homes Impact Insurance Costs and Coverage?
A Paterson has older homes that may require updates to their roofing, electrical, and plumbing systems. Older homes often have outdated wiring, aging plumbing, and roofs beyond their design life, all of which increase claims risk and drive higher premiums. Insurance companies may surcharge or limit coverage unless substantial upgrades have been made. In historic preservation districts, rebuild costs are further elevated because restoration must use matching materials and architectural detail. Investing in system upgrades and documenting improvements may help homeowners qualify for discounts and maintain appropriate coverage.