
Homeowners Insurance Quotes in Tampa, FL
Key Facts About Homeowners Insurance in Tampa
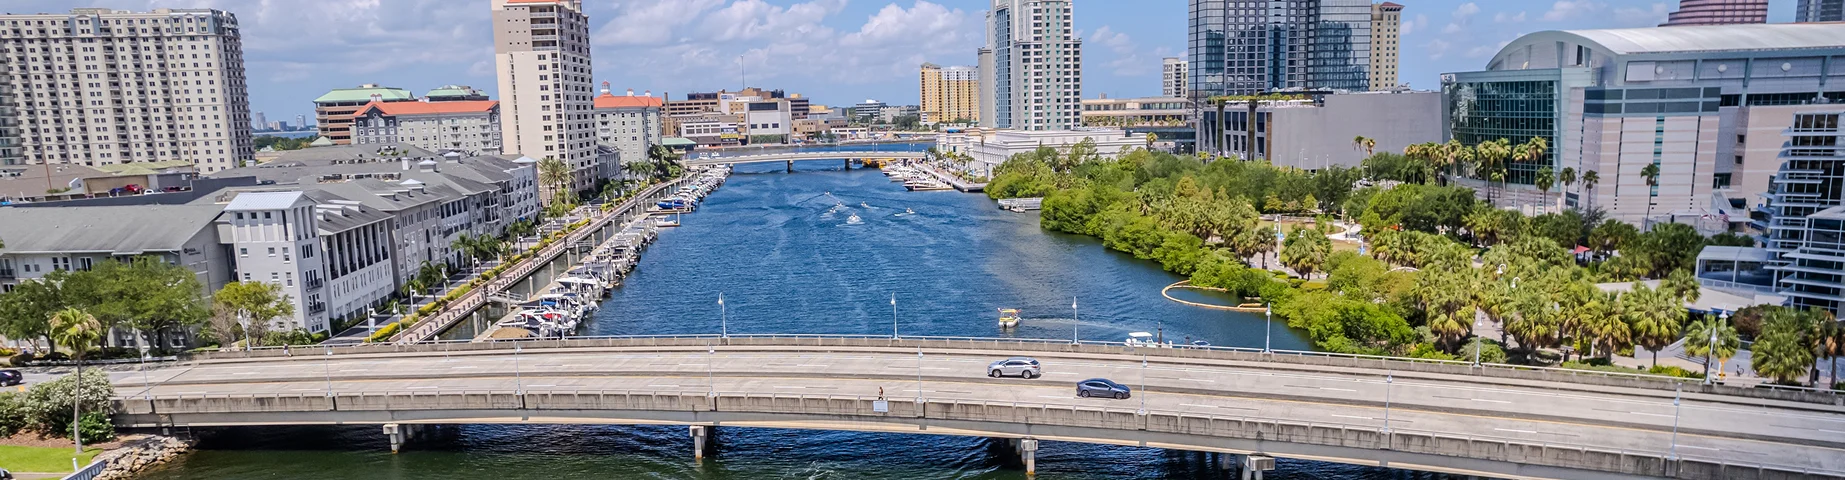
Tampa combines waterfront living, historic neighborhoods, newer master-planned communities, and a growing urban core. Homeowners enjoy access to Tampa Bay and the Gulf Coast, but the same location also creates insurance concerns that are less common in inland markets. Choosing the right Florida homeowners insurance means looking closely at wind exposure, flood risk, rebuilding costs, and the condition of the property.
Housing in Tampa ranges from older homes in Hyde Park and Seminole Heights to newer construction in New Tampa, South Tampa, and Westchase. Each property can require a different approach to coverage. Roof age, building materials, electrical and plumbing systems, elevation, distance from the coast, and wind-mitigation features can all influence eligibility and pricing.
Hurricanes, tropical storms, storm surge, flooding, high winds, lightning, and heavy rain can affect homes throughout the Tampa area. The Atlantic hurricane season officially runs from June 1 through November 30, although storms can occur outside of those dates. Because one major event can damage roofs, windows, siding, detached structures, and personal belongings at the same time, adequate limits and realistic deductibles matter.
A standard homeowners insurance policy can help protect the house, other structures, personal property, additional living expenses, and personal liability when a covered loss occurs. InsureOne can compare Tampa homeowners insurance quotes from multiple carriers and help you review the details that matter for your address instead of relying only on broad citywide averages.
What Does Homeowners Insurance Cost in Tampa?
The average cost of home insurance in Tampa can be higher than rates in many inland areas because insurers account for hurricane exposure, wind losses, coastal weather, and the cost of rebuilding after a widespread disaster. Your actual premium may be above or below an advertised average depending on your home and the coverage you select.
Insurers may review your ZIP code, roof age and shape, construction materials, year built, prior claims, protection devices, and distance from fire services. They also consider the dwelling limit, liability limit, endorsements, deductible, and whether losses are settled at replacement cost or actual cash value. A newer home with updated systems and documented wind-mitigation features may be priced differently from an older property with an aging roof, even when both homes have a similar market value.
The table below shows estimated annual premiums for several common property types. These figures are examples rather than guaranteed quotes, but they provide a useful starting point when comparing homeowners insurance in Tampa.
| Type of Home in Tampa, FL | Average Annual Cost in Tampa, FL | Average Annual Cost in Florida | Average Annual Cost Nationwide |
|---|---|---|---|
| Homes $300K | $2,503 | $3,200 | $2,582 |
| Co-ops and Condos | $1,200 | $1,100 | $1,000 |
| High-end Homes | $7,811 | $8,500 | $7,380 |
These estimates use dwelling coverage, $100,000 in liability protection, and a standard $1,000 deductible. Your quote may change based on the carrier, policy form, hurricane deductible, flood zone, roof requirements, and any optional protection added to the policy.

Comparing Home Insurance Rates in Tampa, FL
Comparing home insurance rates in Tampa is about more than finding the lowest premium. Two policies can have similar prices while offering different deductibles, exclusions, settlement terms, and coverage limits. Review the full policy structure so you understand how much protection you would have after a hurricane, fire, theft, or another covered loss.
Dwelling coverage is usually based on the estimated cost to rebuild the home with comparable materials and labor, not the amount you paid for the property or its current real estate value. As construction costs rise, the limit needed to rebuild may rise as well. This is one reason homeowners should review their replacement cost estimate after major renovations and during annual policy reviews.
| Dwelling Coverage (Tampa, FL) | Average Annual Home Insurance Rates |
|---|---|
| $100,000 | $1,850 |
| $200,000 | $2,750 |
| $300,000 | $3,650 |
| $400,000 | $4,550 |
| $500,000 | $5,450 |
The sample rates reflect the effect that dwelling limits and regional hazards can have on pricing. For a more accurate comparison, request quotes using the same coverage limits and deductibles across carriers. An InsureOne agent can help you compare affordable homeowners insurance in Tampa without overlooking differences that could result in larger out-of-pocket costs after a claim.
Major Risks Tampa Homeowners Should Consider
Insurance companies evaluate regional hazards and details about the individual property when deciding whether to offer coverage and how to price it. Tampa homeowners should pay particular attention to the following risks.
Hurricane and Tropical Storm Exposure
Hurricanes and tropical storms can bring sustained winds, wind-driven rain, falling trees, and flying debris. These conditions may damage roofing, siding, windows, fences, garages, sheds, and other structures. Even homes that are not directly on the coast can experience wind losses from a strong storm moving through the Tampa Bay area.
Florida policies may include a separate hurricane deductible, often calculated as a percentage of the dwelling coverage limit rather than a flat dollar amount. For example, a 2% hurricane deductible on $400,000 of dwelling coverage equals $8,000. Review this amount before purchasing a policy, so you know what you may need to pay after a covered hurricane claim.
Flood and Storm Surge Risks
Flooding can result from storm surge, heavy rainfall, overflowing waterways, or water accumulating faster than drainage systems can handle it. Properties throughout Hillsborough County can face flood exposure, including homes outside the highest-risk flood zones. Elevation and exact location can make a major difference from one street to another.
Standard homeowners policies generally exclude flood damage. Homeowners who want protection for the building and belongings should consider a separate flood insurance policy. Mortgage lenders may also require flood coverage for properties in certain designated flood zones.
Severe Thunderstorms and Lightning
Tampa experiences frequent thunderstorms that can produce strong wind gusts, lightning, hail, and intense rainfall. A single storm may cause roof or window damage, down trees, interrupt power, or allow rain to enter through an opening created by a covered event. Review how the policy handles wind and water damage, since coverage depends on the cause of the loss.
Salt Air, Humidity, and Coastal Conditions
Salt air, heat, humidity, and persistent moisture can accelerate wear on roofing, exterior finishes, metal components, and mechanical systems. Insurance is designed for sudden and accidental covered losses, not gradual deterioration or neglected maintenance. Keeping the home in good condition can reduce preventable damage and may also make it easier to meet carrier underwriting requirements.

Additional Coverage Options for Tampa Homeowners
A standard policy provides broad protection, but it may not address every risk or every item at the limit you need. Tampa homeowners often review endorsements and separate policies to close potential coverage gaps. Depending on your assets and liability exposure, an umbrella insurance policy may also provide additional liability protection above the limits of qualifying home and auto policies.
Extended Replacement Cost Protection
Extended replacement cost coverage may provide an additional percentage above the dwelling limit when the cost to rebuild exceeds the amount listed on the policy. This can be valuable after a major regional disaster, when labor and material demand may increase quickly. Limits and eligibility vary by carrier, so review the endorsement carefully.
Separate Flood Insurance
A separate flood policy can protect the home and, when selected, personal belongings from covered flood losses. Coverage limits, deductibles, waiting periods, and temporary living expense benefits can differ between private flood insurance and policies offered through the National Flood Insurance Program.
Water and Sewer Backup Coverage
Water backup coverage may help pay for covered damage when water or sewage backs up through a drain, sewer line, or sump system. This is different from overland flooding and is usually added as an endorsement with its own limit and deductible.
Roof Replacement Protection
Roof settlement terms can have a major effect on a claim. Some policies pay replacement cost for eligible roofs, while others settle older roofs at actual cash value after depreciation. Ask how roof age, material, inspection results, and wind damage affect coverage before choosing a policy.
Coverage for High-Value Personal Property
Standard policies often place special limits on theft or loss of valuable items. Scheduled personal property coverage can provide broader protection and higher limits for belongings such as the following. InsureOne can also help you explore separate jewelry insurance when the standard policy does not provide enough protection.
- Jewelry
- Watches
- Collectibles
- Fine art
- Electronics
Why Home Insurance Costs Differ Across Tampa
Home insurance costs can vary across Tampa because carriers evaluate the exact property rather than the city name alone. Flood designation, distance from water, year built, roof age, building materials, prior claims, and wind-mitigation features can all affect the final quote. Some homes need more insurance because they would be more expensive to rebuild or have features that require higher limits. In some cases, older homes in Tampa can have insurance premiums over $10,000 because home age and rebuild risk materially affect pricing.
South Tampa Homes
South Tampa includes waterfront and near-water properties as well as homes farther inland. Exact elevation, flood zone, construction type, and distance from the bay can affect flood requirements and wind exposure. Two nearby homes may receive different quotes when one has updated shutters and a newer roof while the other does not.
New Tampa Properties
Many New Tampa properties are newer than homes in the city’s historic districts. Updated construction standards, newer roofs, modern electrical and plumbing systems, and documented wind-mitigation features may improve eligibility or pricing. However, larger square footage and higher replacement costs can still raise the dwelling limit and premium.
Seminole Heights and Other Historic Areas
Older homes in Seminole Heights and other historic areas may include original materials, distinctive architectural details, or aging plumbing, wiring, and roofing. These features can increase rebuilding costs or require inspections and updates before a carrier will issue coverage. Owners should make sure the replacement cost estimate reflects specialized materials rather than only the home’s market value.
Westchase and Master-Planned Neighborhoods
Westchase and other master-planned communities often include newer homes with updated systems and construction features. Gated access, community security, newer roofs, and proximity to fire services may influence pricing, but insurers will still evaluate each address individually, including flood exposure and prior claims.
Homeowners Policy Types Available in Tampa
Homeowners policies are designed for different types of residences and ownership arrangements. Understanding the available forms can make it easier to compare protection, exclusions, and settlement terms. The following are several common policy types, and this overview of types of homeowners insurance can provide additional context.
Policy form is only one part of the decision. You should also compare dwelling and personal property limits, replacement cost versus actual cash value, liability protection, additional living expenses, exclusions, endorsements, and hurricane deductibles. An InsureOne agent can explain how these details affect the protection and price of a Tampa homeowners insurance policy.
- HO-3 policy: This is the most common form for owner-occupied single-family homes. It generally covers the dwelling against all causes of loss except those excluded by the policy, while personal property is covered for listed perils.
- HO-5 policy: This form usually provides broader protection for the home and personal belongings than an HO-3. It may cover personal property on an open-perils basis and often includes replacement cost settlement, subject to policy terms and exclusions.
- HO-6 policy: Designed for condo and co-op owners, this policy can cover personal belongings, interior improvements, loss of use, and liability. The condominium association’s master policy generally covers other parts of the building, so owners should review both policies for gaps.
- HO-7 and HO-8 policies: An HO-7 is designed for mobile or manufactured homes. An HO-8 may be used for certain older homes when traditional replacement with matching materials is unusually difficult or expensive. Coverage is more limited, so compare terms carefully.
Ways To Save on Homeowners Insurance in Tampa
Homeowners may be able to reduce premiums by lowering the property’s risk, qualifying for discounts, and comparing carriers. The best approach is to focus on savings that do not leave you with inadequate limits or an unaffordable deductible. Review these ways to save on homeowners insurance as you evaluate your options.
Common strategies for finding more affordable homeowners insurance in Tampa include:
- Bundling home and auto insurance, which can save 5–15%
- Installing hurricane shutters
- Upgrading to impact-resistant windows
- Replacing aging roofs
- Completing wind mitigation improvements
- Installing security systems
- Maintaining a claims-free history
- Choosing a higher deductible
- Updating plumbing and electrical systems
A wind mitigation inspection can reduce wind coverage premiums by 20% to 45% for some customers. Florida requires discounts for certified wind mitigation features.
Bundling can be useful, but the largest advertised discount does not always produce the lowest total cost. Compare a home and auto insurance bundle against separate policies with equivalent protection. You can also review other insurance bundling options when you need more than one type of coverage.
Before raising your deductible, calculate the amount you would have to pay for an ordinary claim and a hurricane claim. Also ask whether a roof replacement, impact-resistant openings, hurricane shutters, updated plumbing, or a wind-mitigation inspection could qualify the home for better pricing. Reviewing additional home insurance savings tips can help you prepare questions for your agent.

Find Affordable Tampa Homeowners Insurance with InsureOne
Owning a home in Tampa comes with coastal weather risks, rising rebuilding costs, and policy details that deserve careful review. The right coverage should reflect your home’s actual construction, location, value, and exposure instead of relying on a one-size-fits-all package.
InsureOne agents can help you compare Tampa homeowners insurance quotes, review deductibles and endorsements, and look for coverage that fits your needs and budget. Get started online, visit an office near you, or call (800) 836-2240 to request a free quote.
Tampa, FL Homeowners Insurance FAQs
What affects homeowners insurance rates in Tampa?
Rates can be affected by the home’s location, flood and wind exposure, roof age, construction materials, replacement cost, claims history, deductible, coverage limits, and optional endorsements. Wind-mitigation features, security devices, and updated systems may qualify for savings with some carriers.
Does Tampa homeowners insurance cover hurricane damage?
Many standard policies cover wind damage from hurricanes, subject to exclusions, limits, and a separate hurricane deductible. Flooding from storm surge or rising water is generally excluded and requires a separate flood policy.
How can I insure jewelry and other high-value belongings?
Standard policies may limit coverage for jewelry, fine art, collectibles, watches, and other valuables. Scheduling individual items or purchasing specialized coverage can provide higher limits and broader protection, often with an appraisal or proof of value.
How often should Tampa homeowners review their policy?
Review coverage at least once a year and after renovations, roof replacement, major purchases, or changes in who lives in the home. An annual review helps keep dwelling and personal property limits aligned with current rebuilding and replacement costs.