
Homeowners Insurance Quotes in Arlington, TX
What You Should Know About Home Insurance in Arlington, TX
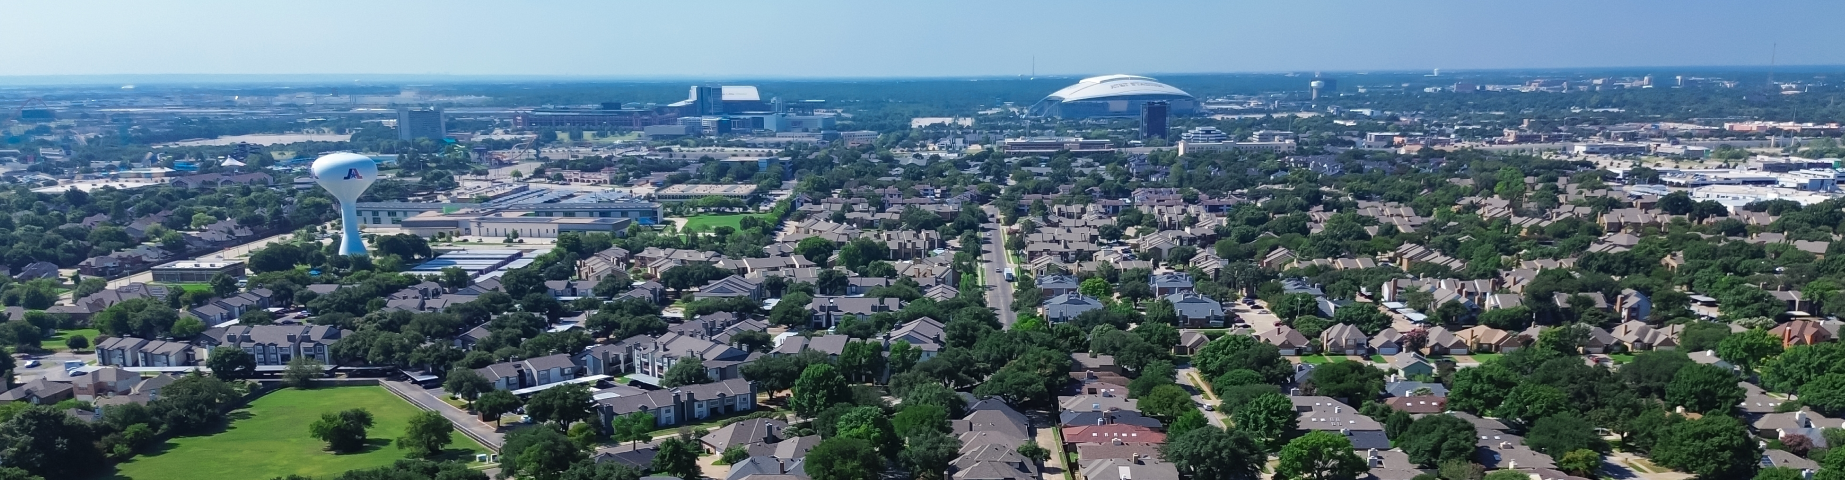
Located between Dallas and Fort Worth, west of Dallas, Arlington spans nearly 96 square miles and is home to about 400,000 residents, making it one of the largest cities in North Texas and one of the fastest-growing U.S. cities. For homeowners looking for home insurance in Arlington, TX, that scale matters: from established homes in North Arlington to newer developments in the southern part of the city, different neighborhoods, property ages, and rebuilding costs can all affect coverage and price.
While Arlington offers convenient access to employment, recreation, and education throughout the Dallas-Fort Worth Metroplex, homeowners also need coverage that takes the city’s volatile weather into account. Severe thunderstorms, hail, high winds, flash flooding, and occasional tornadoes are among the most common local risks, so understanding how home insurance costs, coverage options, and savings opportunities vary across Arlington can help you avoid gaps and compare policies more confidently.
Homeowners insurance is important because it helps protect the hard-earned investment you’ve made in your home, your belongings, and your family while making sure your property is properly covered for damage and liability exposures. Whether you own an older house or a newer build, comparing Texas home insurance quotes with InsureOne is an easy way to request options tailored to different insurance needs, including bundling opportunities and personalized guidance from a local hub for Arlington homeowners seeking the right coverage at a competitive price.
How Much Does Home Insurance Cost in Arlington, TX?
The cost of homeowners insurance in Arlington depends on factors such as your home’s age, construction type, roof condition, claims history, and the specifics of your home insurance policy. Weather-related risks, particularly hail and wind damage, also play a significant role in determining premiums throughout North Texas.
Below are estimated annual premiums based on common dwelling coverage amounts.
| Type of Home | Average Annual Cost in Arlington | Average Annual Cost in Texas | Average Annual Cost Nationwide |
|---|---|---|---|
| Homes with $300K Dwelling Coverage | $4,320–$4,680 | $3,800–$4,100 | $2,300–$2,500 |
| Co-ops and Condos | $850 | $800–$1,000 | $500–$700 |
| Higher-Value Homes with $500K Dwelling Coverage | $6,840–$7,800 | $6,700–$7,000 | $3,500–$4,500 |
We arrived at these numbers by using the cost of dwelling coverage, a $100,000 liability, and a standard $1,000 deductible.

Compare Home Insurance Rates in Arlington, TX
Comparing homeowners insurance rates is key to finding the best coverage at a competitive price, and in Texas those rates can vary significantly by carrier, not just by your home’s characteristics. Below is a table showing the average rates in Texas to help you get started.
| Dwelling Coverage | Average Monthly Rate |
|---|---|
| $100,000 | $140–160 |
| $200,000 | $240–290 |
| $300,000 | $360–390 |
| $400,000 | $470–520 |
| $500,000 | $570–650 |
Comparing quotes from multiple insurance providers is one of the best ways to find competitive rates, and InsureOne does the work of comparing options for Arlington homeowners.
What Risks Affect Arlington Homeowners?
Insurance companies evaluate both property-specific and local risk factors when determining rates.
Severe Hailstorms
Hail is one of the most common causes of homeowners insurance claims in Arlington. Large hailstones can damage:
- Roofing materials
- Gutters
- Siding
- Windows
- HVAC equipment
Many Arlington homeowners choose enhanced roof coverage or replacement cost endorsements because of the area’s frequent hail activity. Deductibles for windstorm damage can be higher than deductibles for other covered losses.
Wind and Tornado Activity
Arlington experiences severe thunderstorms capable of producing damaging straight-line winds and occasional tornadoes. These storms can result in structural damage, fallen trees, and power outages.
Flash Flooding
Heavy rainfall can overwhelm drainage systems and low-lying areas throughout Tarrant County. Standard homeowners insurance policies generally do not cover flood damage. If coverage is hard to secure for a higher-risk property, the Texas FAIR Plan may offer limited insurance as a last-resort option.
Aging Housing Stock
Many Arlington neighborhoods contain homes built in the 1960s, 1970s, and 1980s. Older plumbing, electrical systems, and roofs may increase insurance costs if they have not been updated.
Coverage Arlington Homeowners Often Consider
While every homeowner’s needs are different, Arlington homeowners often consider extra options because property insurance can be customized with endorsements for specific needs, which means adding optional coverage can raise protection levels for the gaps a standard policy may leave.
Extended Replacement Cost Coverage
Provides additional protection if rebuilding costs exceed your dwelling coverage limit following a major loss.
Water Backup Coverage
Helps cover damage caused by sewer backups or drain overflows that are typically excluded from standard policies.
Roof Replacement Coverage
Can help cover the full replacement cost of a damaged roof rather than a depreciated value settlement.
Flood Insurance
Provides protection against flood-related damage that is excluded from most homeowners policies.
Scheduled Personal Property Coverage
Offers additional protection for valuable belongings such as:
- Jewelry
- Firearms
- Collectibles
- Fine art
- Electronics
Standard homeowners insurance policies often place low sub limits on certain high-value items kept in your place. If you own expensive belongings, consider scheduling them separately or choosing replacement cost coverage to avoid standard policy limits and depreciation.

How Home Insurance Costs Can Vary Across Arlington
Insurance premiums can differ significantly throughout Arlington based on local conditions.
North Arlington
Many homes are older and may have aging roofs, plumbing, or electrical systems that can impact rates.
South Arlington
Newer developments often benefit from updated building materials and modern construction standards, which may help reduce certain insurance risks.
Lake Arlington Area
Properties near water may have different insurance considerations, including flood exposure and higher property values.
Entertainment District and Higher-Value Properties
Homes near AT&T Stadium, Globe Life Field, and the University of Texas at Arlington often have higher replacement costs and may require higher dwelling and liability limits. Properties near River Legacy Park may also face different risk factors depending on location.
Types of Home Insurance in Arlington, TX
There are several types of homeowners insurance coverage available, and the options generally vary based on the level of protection you want for your home and belongings. In most areas, you’ll find the following common types:
- Basic Coverage ‑ This typically covers the structure of your home and personal belongings in the event of damage or loss from common perils like fire, theft, or vandalism. It’s the most affordable option but offers the least protection.
- Broad Coverage ‑ This offers more protection than basic coverage, including additional risks like falling objects or water damage from broken pipes. It’s a good middle ground for homeowners seeking more security.
- Specialized or Comprehensive Coverage ‑ This provides the highest level of protection, covering most perils unless specifically excluded. It typically includes everything from structural damage to personal property loss, including more unique situations like accidental damage to expensive items.
- Renters Insurance ‑ While not for homeowners, renters insurance is available for those who are renting property. It covers personal belongings in case of damage or theft but doesn’t cover the building itself.
- Flood Insurance ‑ Standard home insurance doesn’t cover flood damage, so if you live in a flood‑prone area, it’s a good idea to consider adding this separate coverage to protect your home from water damage.
Selecting the appropriate type of coverage is based on the value of your home, its contents, and your comfort level with risk. Many homeowners choose broad coverage to protect themselves against a wide variety of potential issues.
How Can Arlington Homeowners Save on Insurance?
Many homeowners can reduce insurance costs through available discounts and proactive home improvements.
Common savings opportunities include:
- Installing monitored security systems
- Adding smoke detectors and fire alarms
- Replacing older roofs
- Installing impact-resistant roofing materials
- Upgrading plumbing and electrical systems
- Maintaining a claims-free history
- Selecting a higher deductible
- Using smart leak detection devices
- Completing approved home safety courses, which some insurers discount
Bundling your home and auto insurance in Arlington is a great way to save money. Many insurers offer discounts of 10% to 25% when you combine both policies with the same company. Comparing bundled and separate policy options may also help lower your premiums while keeping the coverage you need. Plus, it makes managing your insurance easier: you’ll have only one provider and one payment to keep track of.
Since discounts vary by insurer, talk with an InsureOne agent about available discounts and eligibility while reviewing Arlington homeowners insurance quotes.

Get the Best Homeowners Insurance in Arlington with InsureOne Today
Protecting your home with the right insurance is especially important for Arlington families and homeowners in a city where about 55% of residents own and roughly 45% rent. Whether you’re looking for basic protection or comprehensive coverage, we’re here to help you find the best policy to fit your needs. Arlington has over 800 insurance agents available, but InsureOne can serve as one local hub for comparing options. To get started, visit us online for a free quote, stop by an office near you, or call our experts at (800) 836‑2240. At InsureOne, we’re dedicated to helping Texans protect what matters most.
Frequently Asked Questions About Home Insurance in Arlington, TX
What Factors Affect Home Insurance Rates in Arlington, TX?
Home insurance rates in Arlington are influenced by several factors, including the age and condition of your home, its location within the city, the coverage limits you choose, and your claims history. Weather risks like hail, windstorms, and tornadoes also play a vital role in setting premiums.
Is Homeowners Insurance Required in Arlington?
Homeowners insurance isn’t legally required in Arlington, TX, but it’s strongly recommended to protect your investment. Mortgage lenders usually require it to cover damage from hail, windstorms, fire, and theft. Even if you own your home outright, insurance offers financial protection against accidents and liability claims. Renters should also consider renters insurance for belongings and liability. Local agents can help find affordable policies that meet your needs and provide peace of mind.
Do Arlington Homeowners Need Flood Insurance?
Yes, many Arlington homeowners should get flood insurance. Standard policies usually exclude flood damage, which is a real risk due to flash flooding and heavy rain. Flood insurance covers water damage to your home and belongings. Given Arlington’s low-lying areas and drainage issues, flood coverage is essential for full protection. Consult an agent to assess your flood risk and coverage options.
Why Are Home Insurance Costs Higher in Arlington?
Home insurance costs in Arlington are above the national average due to severe weather risks like hail, tornadoes, and flooding. Older homes with aging roofs and systems also raise premiums. Local rebuilding costs, theft, vandalism risks, and market factors contribute to higher rates. Knowing these helps homeowners choose coverage that fits their needs while managing costs.
What Deductible Is Common for Arlington Homeowners?
Many Arlington homeowners choose deductibles ranging from $1,000 to $2,500, although some policies may include separate wind or hail deductibles. The right deductible depends on your budget and risk tolerance.